Mon - Sat 8.00 - 18.00 Sunday CLOSEDOur Address11 Wall St, New York
Tel: 530-666-6671 Pay With Square

July 9, 2021by admin

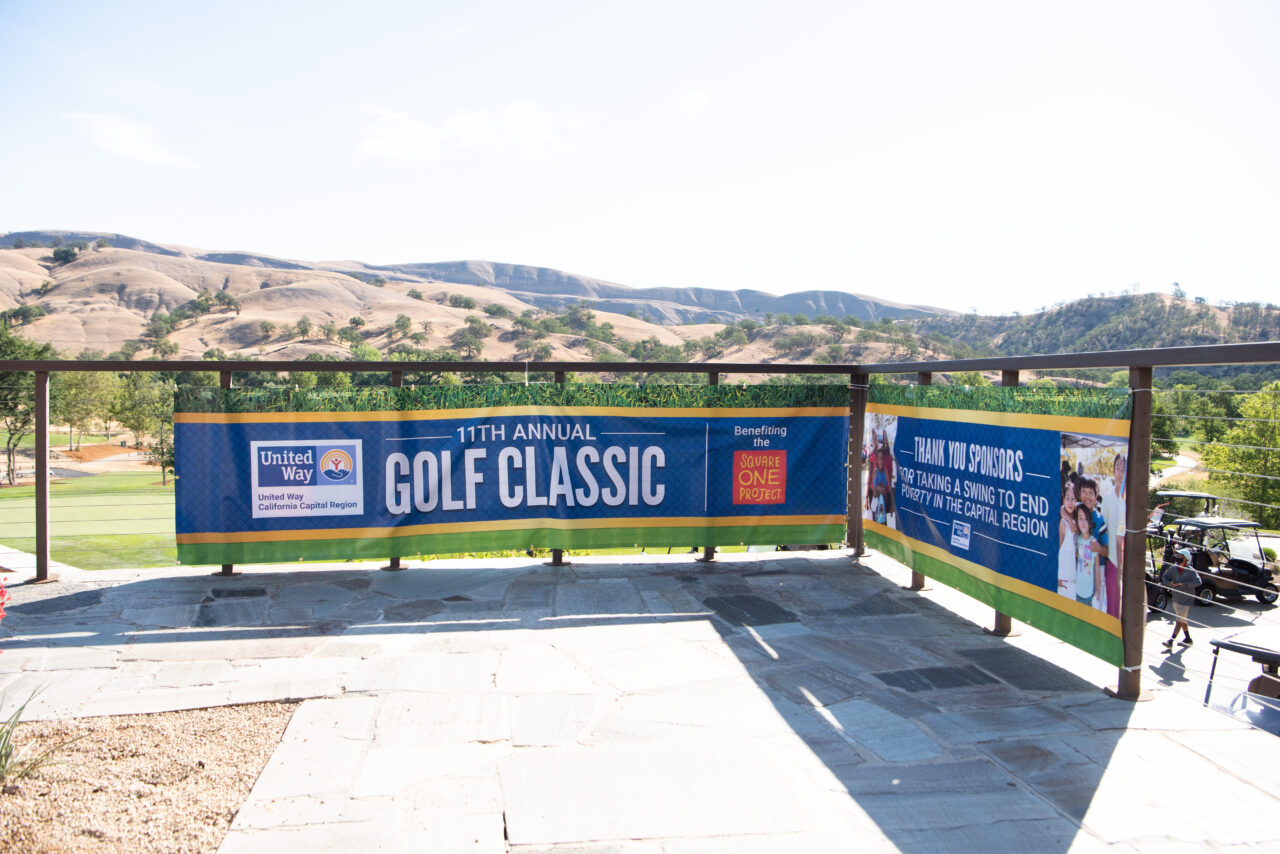
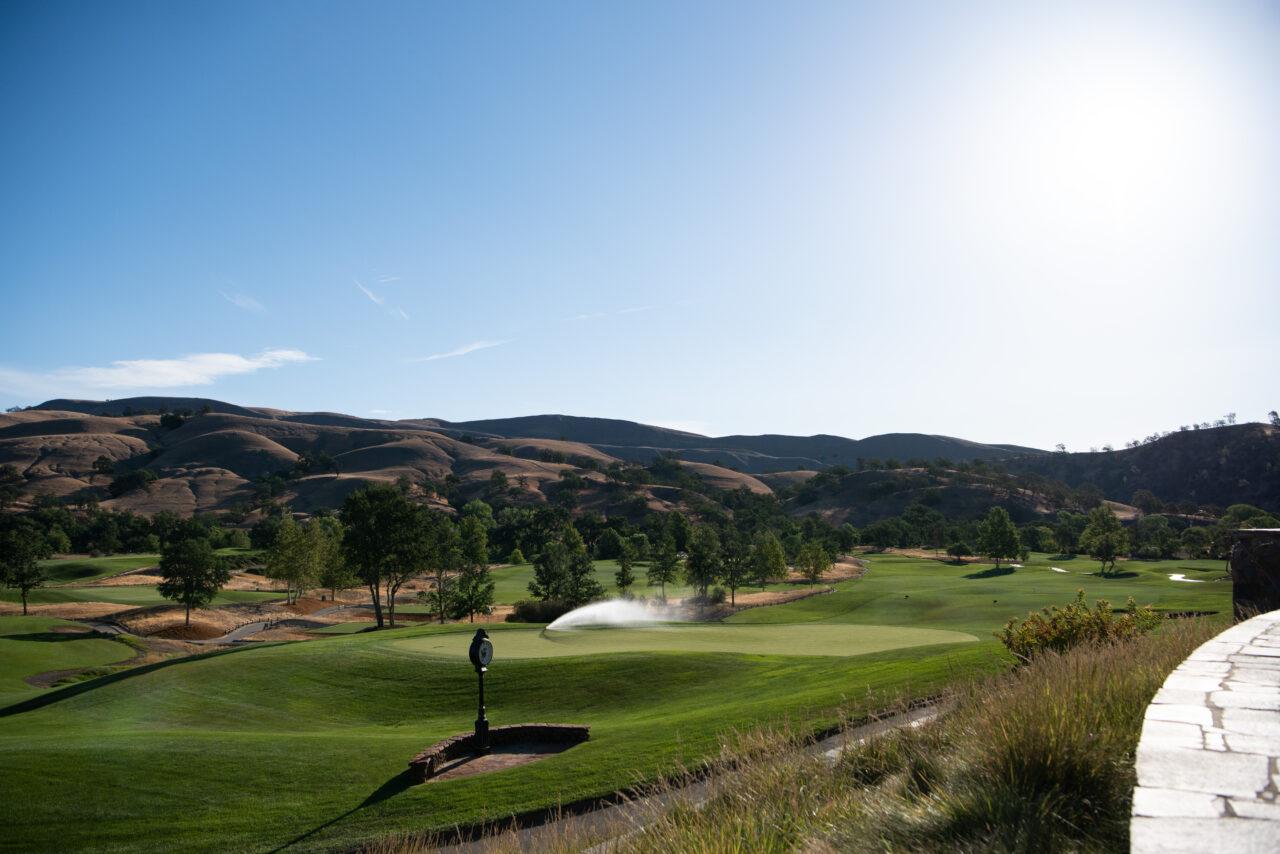
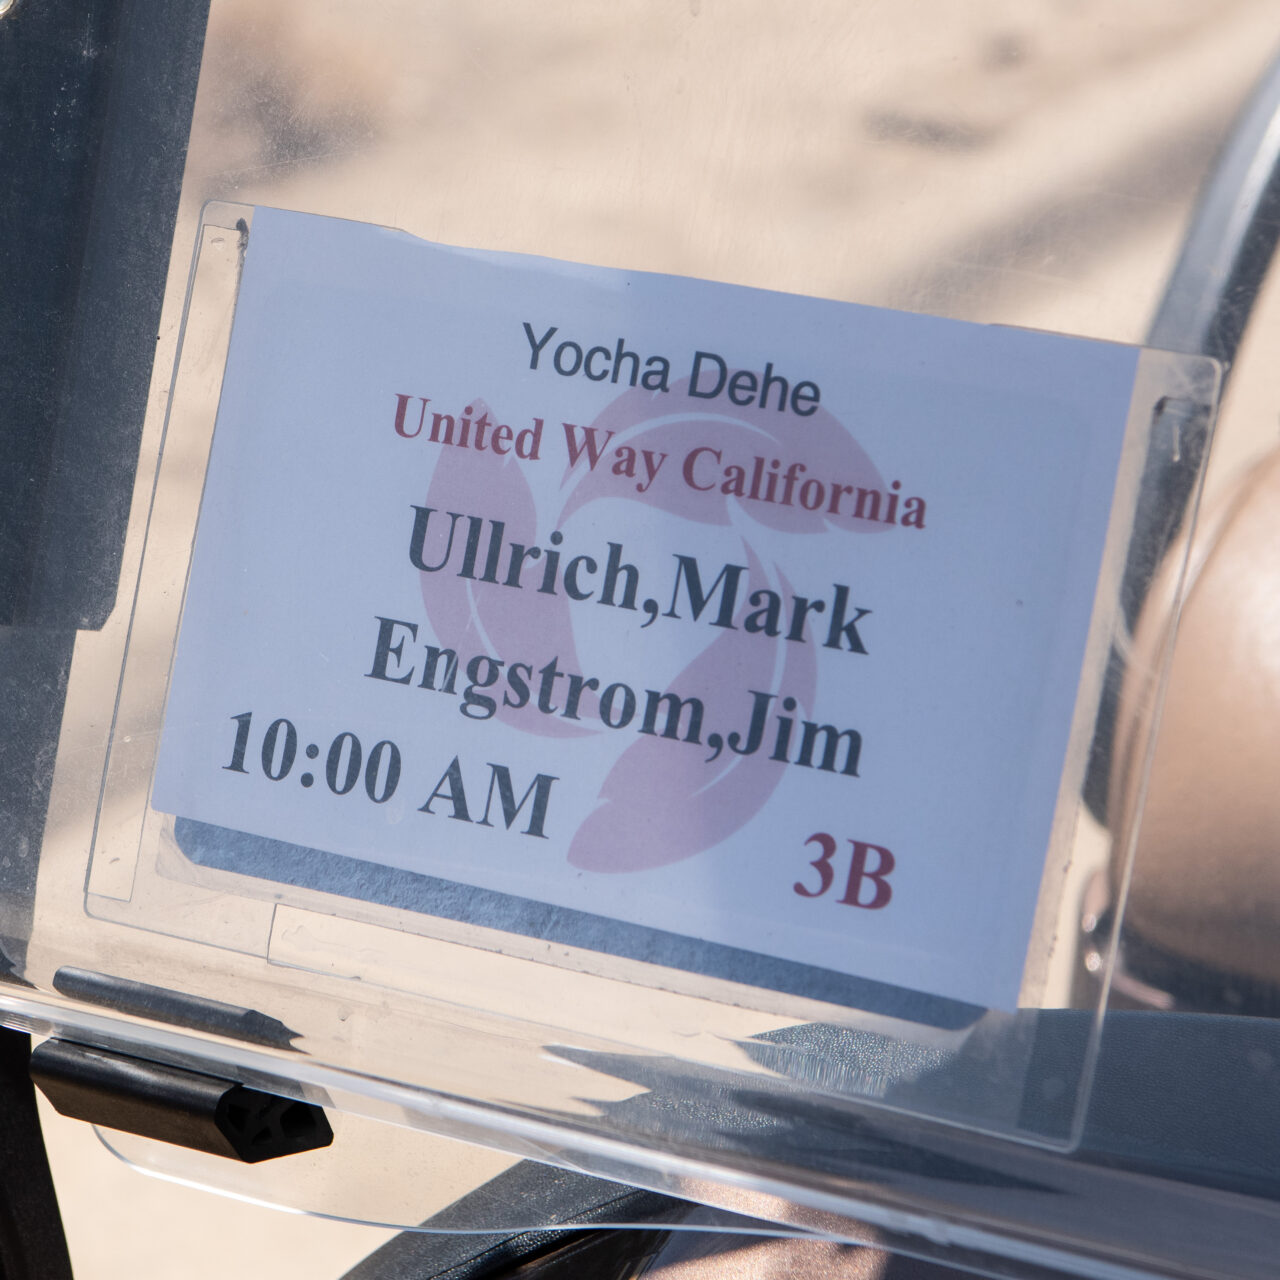
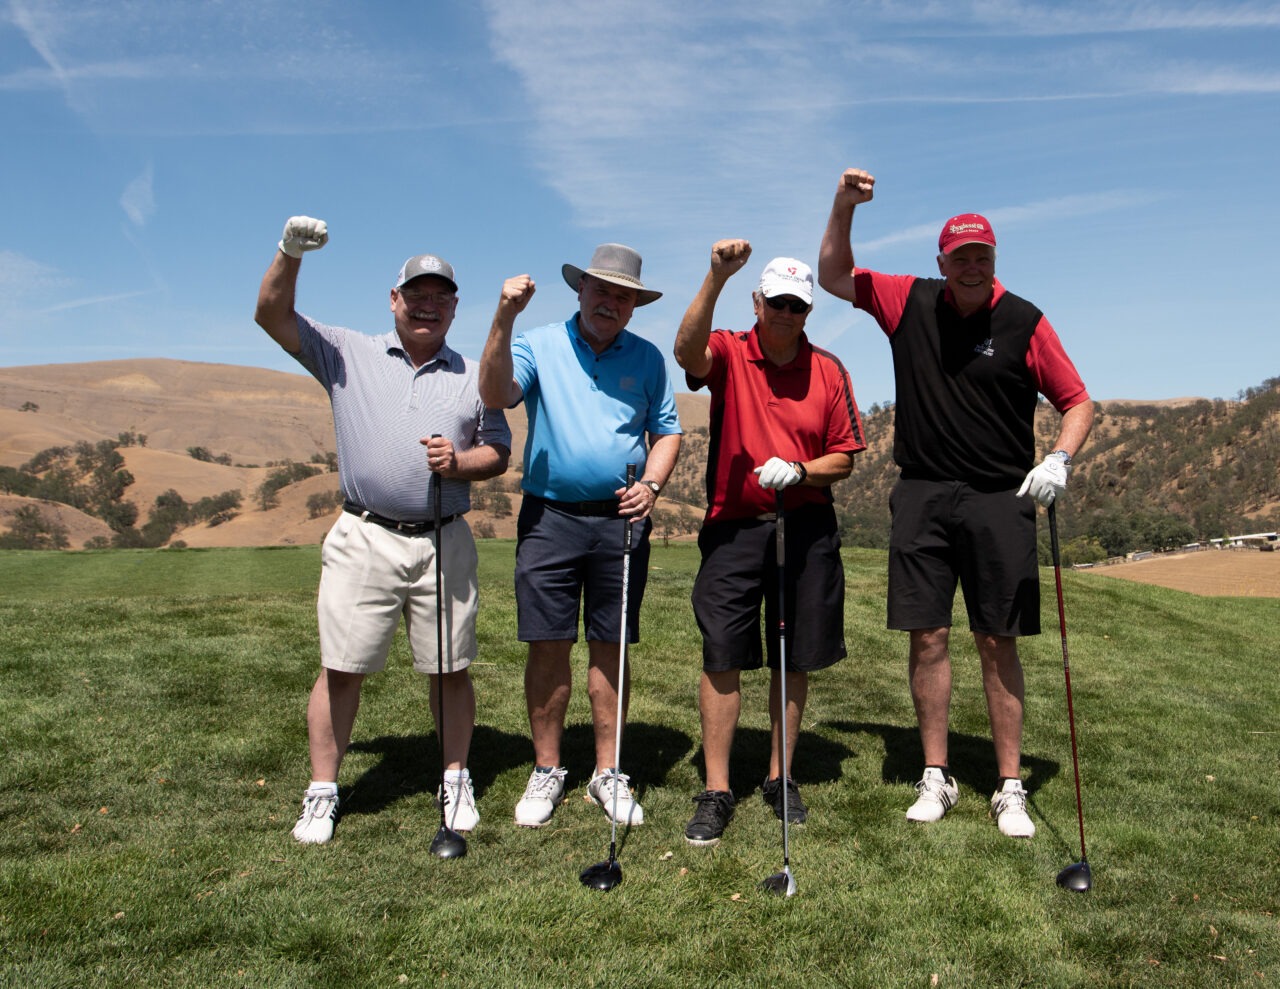
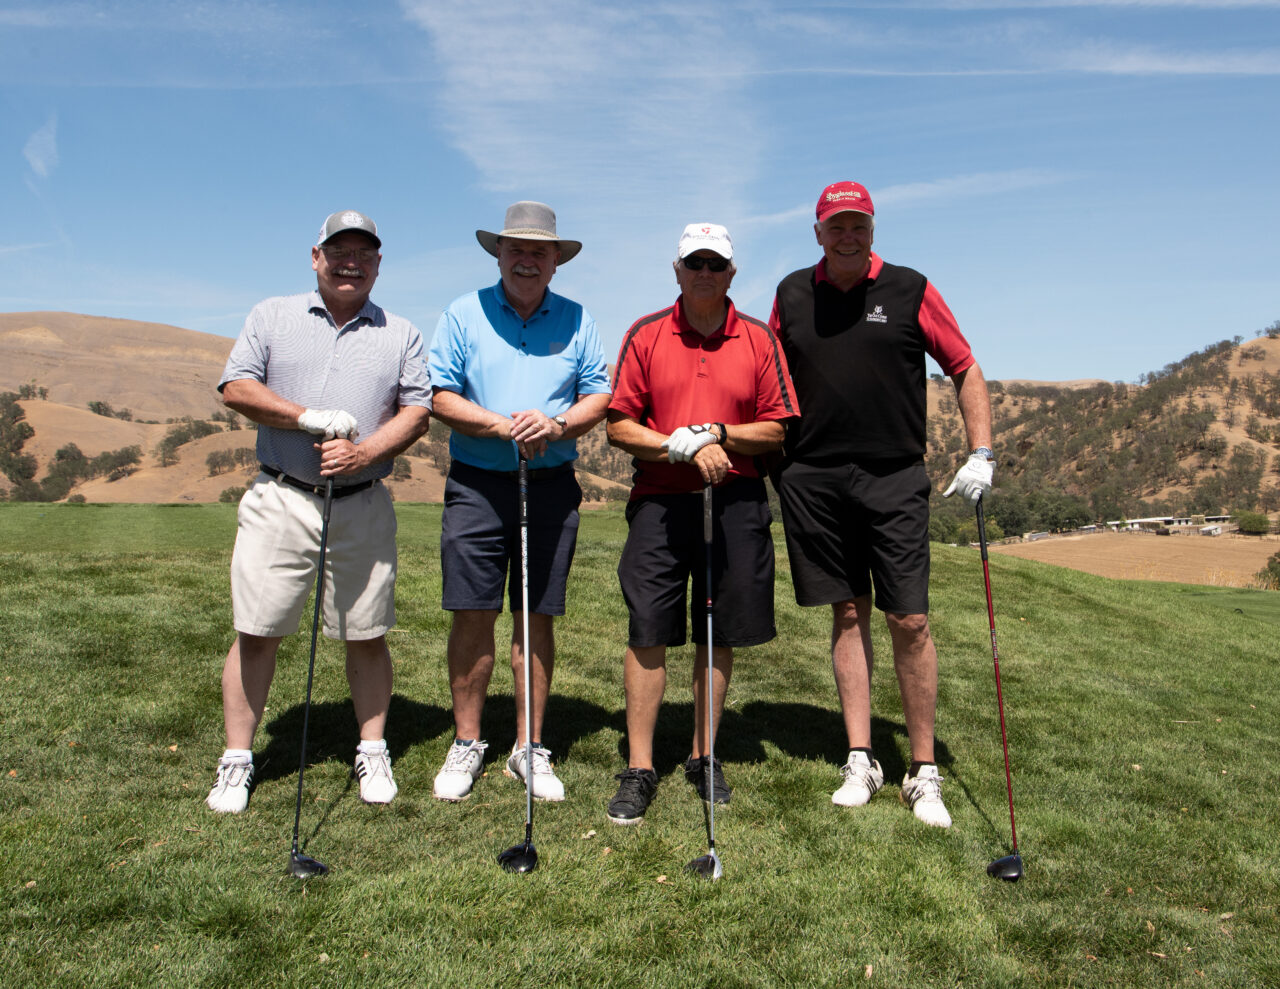
We were honored to serve as a TEE/GREEN Sponsor for the 11th Annual United Way Golf Classic on June 11, 2021, at the beautiful Yocha Dehe Golf Club. Along with the other sponsors and tournament participants, the event and helped raise over $58,000 for the Square One Project!

Thank you to all who participated and to the United Way California Capital Region for hosting this incredible event!

Here are some photos of the event and our foursome, we invite you to scroll though!  We have also shared some links to help you learn more about the event and view additional photo galleries of our fellow sponsors and participants.

Golf2
Golf5
Golf4
Golf1
Golf3


Photos of all the golfers who participated:  https://www.flickr.com/photos/75654771@N08/albums/72157719417892216
If you look closely, you’ll even see some photos of the Sac Republic soccer players in front of our Tee sign!

Event photos: https://www.flickr.com/photos/75654771@N08/albums/72157719467368570
In true style, the United Way California Capital Region and fellow tournament sponsors put on an incredible event!  The Yocha Dehe Golf Club is also a sight to behold.  A wonderful time was had by all!

11th Annual Golf Classic Event Page: https://www.yourlocalunitedway.org/post/golfers-take-swing-ending-poverty

Sponsorship Appreciation Page: https://www.yourlocalunitedway.org/golf-sponsor-appreciation

We’re already looking forward to next year!


Taxes-Due-538x218.jpg

July 1, 2021by admin

July 12, 2021

Employees – who work for tips. If you received $20 or more in tips during June, report them to your employer. You can use Form 4070.

July 15, 2021

Employers – Social Security, Medicare, and withheld income tax. If the monthly deposit rule applies, deposit the tax for payments in June.

Employers – Nonpayroll withholding. If the monthly deposit rule applies, deposit the tax for payments in June.


clay-banks-Ox6SW103KtM-unsplash-1280x854.jpg

June 4, 2021by admin

It’s a safe bet that state tax authorities will let you know if your business hasn’t paid enough sales and use taxes. But the lines of communication may not be so open if you’re overpaying. For this reason, many businesses use reverse audits to find overpayments so they can seek reimbursements.

In most states, businesses are exempt from sales tax on equipment used in manufacturing or recycling, and many states don’t require them to pay taxes on the utilities and chemicals used in these processes, either. In some states, custom software and other computer equipment are exempt if used for research and development projects. These are just a few examples of potentially available exemptions.

Many companies have sales and use tax compliance systems to guard against overpaying, but if you haven’t reviewed yours recently, check to make sure it’s functioning properly. Employee turnover, business expansion or downsizing, and simple mistakes all can take their toll.

A formal reverse audit can extend across your business, going back as far as the statute of limitations on state tax reviews. If your state auditors can review all records for the four years preceding the audit, for example, the audit could encompass the same timeframe.

To be clear, reverse audits are often time consuming and complex. But a well-executed one can not only reap tax refund rewards now, but also help update your compliance systems going forward. Let us help you target the exemptions available to your business and ensure refund claims are properly prepared before submittal.


05_31_21_459375129_SBTB_560x292.jpg

June 4, 2021by admin

If you’re a business owner and you hire your children this summer, you can obtain tax breaks and other nontax benefits. The kids can gain on-the-job experience, spend time with you, save for college and learn how to manage money. And you may be able to:

  • Shift your high-taxed income into tax-free or low-taxed income,
  • Realize payroll tax savings (depending on the child’s age and how your business is organized), and
  • Enable retirement plan contributions for the children.

A legitimate job

If you hire your child, you get a business tax deduction for employee wage expenses. In turn, the deduction reduces your federal income tax bill, your self-employment tax bill (if applicable), and your state income tax bill (if applicable). However, in order for your business to deduct the wages as a business expense, the work performed by the child must be legitimate and the child’s salary must be reasonable.

For example, let’s say you operate as a sole proprietor and you’re in the 37% tax bracket. You hire your 16-year-old daughter to help with office work on a full-time basis during the summer and part-time into the fall. Your daughter earns $10,000 during 2021 and doesn’t have any other earnings.

You save $3,700 (37% of $10,000) in income taxes at no tax cost to your daughter, who can use her 2021 $12,550 standard deduction to completely shelter her earnings.

Your family’s taxes are cut even if your daughter’s earnings exceed her standard deduction. Why? The unsheltered earnings will be taxed to the daughter beginning at a rate of 10%, instead of being taxed at your higher rate.

How payroll taxes might be saved

If your business isn’t incorporated, your child’s wages are exempt from Social Security, Medicare and FUTA taxes if certain conditions are met. Your child must be under age 18 for this to apply (or under age 21 in the case of the FUTA tax exemption). Contact us for how this works.

Be aware that there’s no FICA or FUTA exemption for employing a child if your business is incorporated or a partnership that includes nonparent partners. And payments for the services of your child are subject to income tax withholding, regardless of age, no matter what type of entity you operate.

Begin saving for retirement

Your business also may be able to provide your child with retirement benefits, depending on the type of plan you have and how it defines qualifying employees. And because your child has earnings from his or her job, he can contribute to a traditional IRA or Roth IRA and begin to build a nest egg. For the 2021 tax year, a working child can contribute the lesser of his or her earned income, or $6,000, to an IRA or a Roth.

Keep accurate records 

As you can see, hiring your child can be a tax-smart idea. Be sure to keep the same records as you would for other employees to substantiate the hours worked and duties performed (such as timesheets and job descriptions). Issue your child a Form W-2. Contact us if you have questions about how these rules apply to your situation.


pexels-photo-1314544-1280x853.jpeg

June 1, 2021by admin

June 10, 2021

Employees – who work for tips. If you received $20 or more in tips during May, report them to your employer. You can use Form 4070.

June 15, 2021

Individuals – If you are a U.S. citizen or resident alien living and working (or on military duty) outside the United States and Puerto Rico, file Form 1040 or Form 1040-SR and pay any tax, interest, and penalties due. If you want additional time to file your return, file Form 4868 to obtain 4 additional months to file. Then file Form 1040 or Form 1040-SR by October 15.

However, if you are a participant in a combat zone you may be able to further extend the filing deadline.

Individuals – Make a payment of your 2021 estimated tax if you are not paying your income tax for the year through withholding (or will not pay in enough tax that way). Use Form 1040-ES. This is the second installment date for estimated tax in 2021.

Corporations – Deposit the second installment of estimated income tax for 2021. A worksheet, Form 1120-W, is available to help you estimate your tax for the year.

Employers – Nonpayroll withholding.If the monthly deposit rule applies, deposit the tax for payments in May.

Employers- Social Security, Medicare, and withheld income tax. If the monthly deposit rule applies, deposit the tax for payments in May.


HSA.jpg

May 25, 2021by admin

The IRS recently released guidance providing the 2022 inflation-adjusted amounts for Health Savings Accounts (HSAs).

Fundamentals of HSAs

An HSA is a trust created or organized exclusively for the purpose of paying the “qualified medical expenses” of an “account beneficiary.” An HSA can only be established for the benefit of an “eligible individual” who is covered under a “high deductible health plan.” In addition, a participant can’t be enrolled in Medicare or have other health coverage (exceptions include dental, vision, long-term care, accident and specific disease insurance).

A high deductible health plan (HDHP) is generally a plan with an annual deductible that isn’t less than $1,000 for self-only coverage and $2,000 for family coverage. In addition, the sum of the annual deductible and other annual out-of-pocket expenses required to be paid under the plan for covered benefits (but not for premiums) can’t exceed $5,000 for self-only coverage, and $10,000 for family coverage.

Within specified dollar limits, an above-the-line tax deduction is allowed for an individual’s contribution to an HSA. This annual contribution limitation and the annual deductible and out-of-pocket expenses under the tax code are adjusted annually for inflation.

Inflation adjustments for next year

In Revenue Procedure 2021-25, the IRS released the 2022 inflation-adjusted figures for contributions to HSAs, which are as follows:

Annual contribution limitation. For calendar year 2022, the annual contribution limitation for an individual with self-only coverage under a HDHP will be $3,650. For an individual with family coverage, the amount will be $7,300. This is up from $3,600 and $7,200, respectively, for 2021.

High deductible health plan defined. For calendar year 2022, an HDHP will be a health plan with an annual deductible that isn’t less than $1,400 for self-only coverage or $2,800 for family coverage (these amounts are unchanged from 2021). In addition, annual out-of-pocket expenses (deductibles, co-payments, and other amounts, but not premiums) won’t be able to exceed $7,050 for self-only coverage or $14,100 for family coverage (up from $7,000 and $14,000, respectively, for 2021).

Many advantages

There are a variety of benefits to HSAs. Contributions to the accounts are made on a pre-tax basis. The money can accumulate tax free year after year and be can be withdrawn tax free to pay for a variety of medical expenses such as doctor visits, prescriptions, chiropractic care and premiums for long-term care insurance. In addition, an HSA is “portable.” It stays with an account holder if he or she changes employers or leaves the workforce. If you have questions about HSAs at your business, contact your employee benefits and tax advisors.

scorp.jpg

May 25, 2021by admin

If your business is organized as a sole proprietorship or as a wholly owned limited liability company (LLC), you’re subject to both income tax and self-employment tax. There may be a way to cut your tax bill by conducting business as an S corporation.

Fundamentals of self-employment tax

The self-employment tax is imposed on 92.35% of self-employment income at a 12.4% rate for Social Security up to a certain maximum ($142,800 for 2021) and at a 2.9% rate for Medicare. No maximum tax limit applies to the Medicare tax. An additional 0.9% Medicare tax is imposed on income exceeding $250,000 for married couples ($125,000 for married persons filing separately) and $200,000 in all other cases.

What if you conduct your business as a partnership in which you’re a general partner? In that case, in addition to income tax, you’re subject to the self-employment tax on your distributive share of the partnership’s income. On the other hand, if you conduct your business as an S corporation, you’ll be subject to income tax, but not self-employment tax, on your share of the S corporation’s income.

An S corporation isn’t subject to tax at the corporate level. Instead, the corporation’s items of income, gain, loss and deduction are passed through to the shareholders. However, the income passed through to the shareholder isn’t treated as self-employment income. Thus, by using an S corporation, you may be able to avoid self-employment income tax.

Keep your salary “reasonable”

Be aware that the IRS requires that the S corporation pay you reasonable compensation for your services to the business. The compensation is treated as wages subject to employment tax (split evenly between the corporation and the employee), which is equivalent to the self-employment tax. If the S corporation doesn’t pay you reasonable compensation for your services, the IRS may treat a portion of the S corporation’s distributions to you as wages and impose Social Security taxes on the amount it considers wages.

There’s no simple formula regarding what’s considered reasonable compensation. Presumably, reasonable compensation is the amount that unrelated employers would pay for comparable services under similar circumstances. There are many factors that should be taken into account in making this determination.

Converting from a C corporation

There may be complications if you convert a C corporation to an S corporation. A “built-in gains tax” may apply when you dispose of appreciated assets held by the C corporation at the time of the conversion. However, there may be ways to minimize its impact.

Many factors to consider

Contact us if you’d like to discuss the factors involved in conducting your business as an S corporation, and how much the business should pay you as compensation.


employeecontractor.jpg

May 25, 2021by admin

Many businesses use independent contractors to help keep their costs down. If you’re among them, make sure that these workers are properly classified for federal tax purposes. If the IRS reclassifies them as employees, it can be a costly error.

It can be complex to determine whether a worker is an independent contractor or an employee for federal income and employment tax purposes. If a worker is an employee, your company must withhold federal income and payroll taxes, pay the employer’s share of FICA taxes on the wages, plus FUTA tax. A business may also provide the worker with fringe benefits if it makes them available to other employees. In addition, there may be state tax obligations.

On the other hand, if a worker is an independent contractor, these obligations don’t apply. In that case, the business simply sends the contractor a Form 1099-NEC for the year showing the amount paid (if it’s $600 or more).

What are the factors the IRS considers?

Who is an “employee?” Unfortunately, there’s no uniform definition of the term.

The IRS and courts have generally ruled that individuals are employees if the organization they work for has the right to control and direct them in the jobs they’re performing. Otherwise, the individuals are generally independent contractors. But other factors are also taken into account including who provides tools and who pays expenses.

Some employers that have misclassified workers as independent contractors may get some relief from employment tax liabilities under Section 530. This protection generally applies only if an employer meets certain requirements. For example, the employer must file all federal returns consistent with its treatment of a worker as a contractor and it must treat all similarly situated workers as contractors.

Note: Section 530 doesn’t apply to certain types of workers.

Should you ask the IRS to decide?

Be aware that you can ask the IRS (on Form SS-8) to rule on whether a worker is an independent contractor or employee. However, be aware that the IRS has a history of classifying workers as employees rather than independent contractors.

Businesses should consult with us before filing Form SS-8 because it may alert the IRS that your business has worker classification issues — and it may unintentionally trigger an employment tax audit.

It may be better to properly treat a worker as an independent contractor so that the relationship complies with the tax rules.

Workers who want an official determination of their status can also file Form SS-8. Disgruntled independent contractors may do so because they feel entitled to employee benefits and want to eliminate self-employment tax liabilities.

If a worker files Form SS-8, the IRS will notify the business with a letter. It identifies the worker and includes a blank Form SS-8. The business is asked to complete and return the form to the IRS, which will render a classification decision.

These are the basic tax rules. In addition, the U.S. Labor Department has recently withdrawn a non-tax rule introduced under the Trump administration that would make it easier for businesses to classify workers as independent contractors. Contact us if you’d like to discuss how to classify workers at your business. We can help make sure that your workers are properly classified.